Hurricane Isaias has come and gone, but for many Florida families, the cleanup is just beginning.
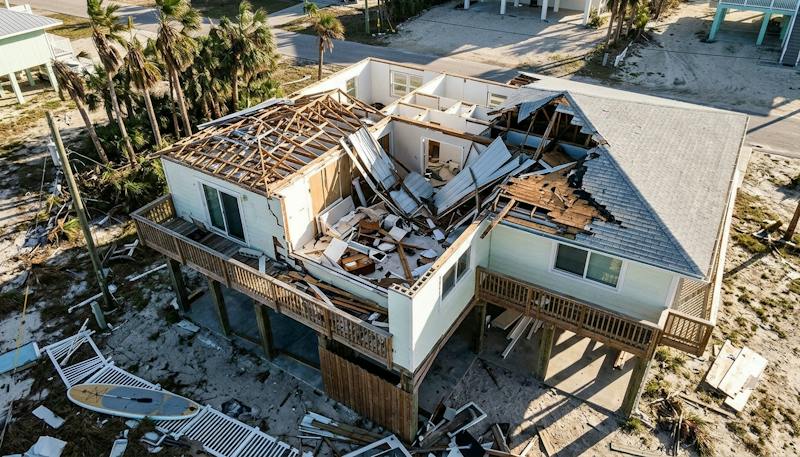
From damaged roofs to fallen trees and flooded homes, the storm left communities across Florida's Panhandle facing serious damage. Now, many homeowners are asking one important question: Will my insurance cover the repairs?
If Hurricane Isaias damaged your home or business, knowing what steps to take can make a big difference.
Hurricane Isaias Leaves Behind Major Storm Damage in Florida
On October 9, 2026, Hurricane Isaias made landfall near Destin, Florida, as a Category 2 hurricane, bringing winds of up to 105 mph.
Isaias was the first hurricane of the 2026 Atlantic hurricane season. It briefly became a Category 3 major hurricane before weakening as it reached the Florida coast.
The storm affected communities across the Florida Panhandle, including Pensacola, Milton, Destin, Fort Walton Beach, and Panama City Beach.
According to FOX Weather, the hurricane brought powerful winds, heavy rain, flooding, and a threat of tornadoes. Some areas experienced wind gusts of more than 110 mph.
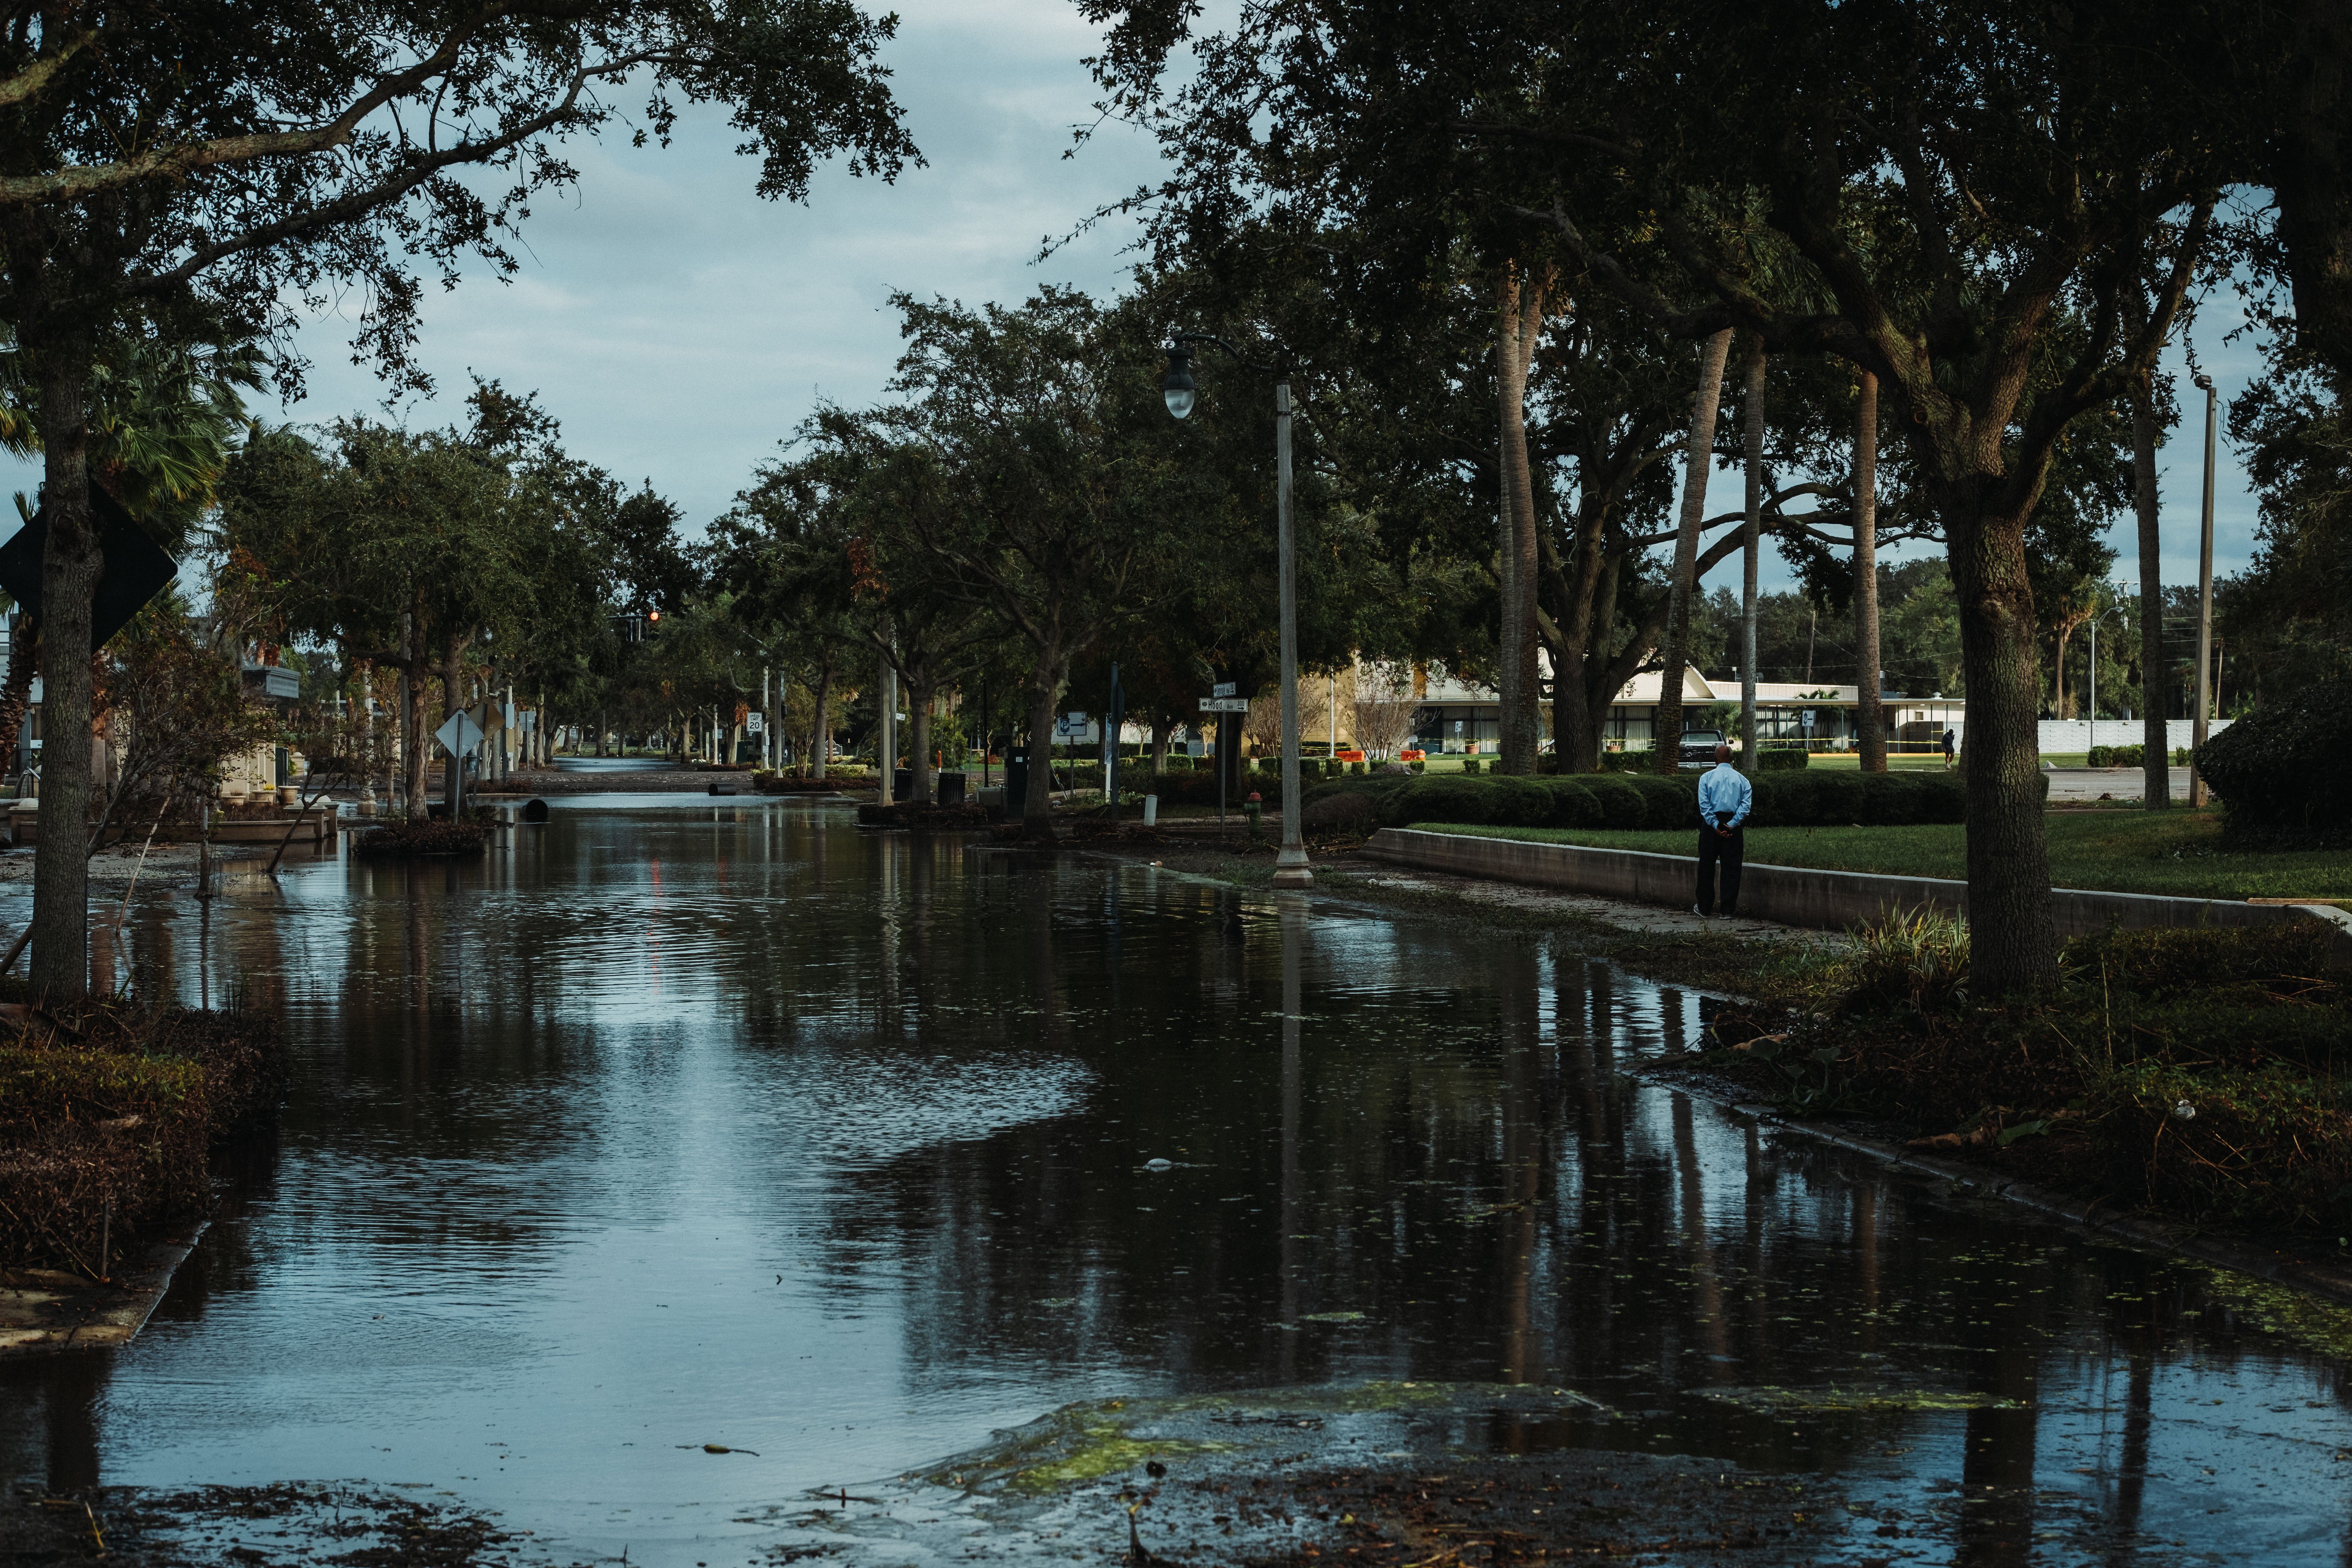
In Escambia County, where Pensacola is located, fallen trees and debris left roads blocked and homes damaged. Panama City Beach also saw water rise about 5.6 feet above the average high tide.
Florida's Gulf Coast is no stranger to powerful storms. Hurricane Sally brought severe flooding to the Panhandle in 2020, while Hurricane Milton struck Florida's central Gulf Coast in 2024.
Although each storm is different, they all show how quickly hurricanes can put homes and families at risk.
For many Florida property owners, recovering from Hurricane Isaias could take weeks or even months.
What Types of Property Damage Did Hurricane Isaias Cause?
Hurricanes can damage homes in many ways. Sometimes, the problems are easy to spot. Other times, damage may not appear until days or weeks later.
Some common types of hurricane damage include:
- 1
Roof damage. Strong winds can tear off shingles, damage roofing materials, or create openings that allow rain inside.
- 2
Water damage. Rain entering through a storm-damaged roof or window can damage ceilings, walls, and floors.
- 3
Fallen trees. Trees and large branches can fall onto homes, garages, and other structures.
- 4
Window and door damage. Flying debris and strong winds can break windows or damage doors.
- 5
Structural damage. Powerful winds can damage siding, walls, and other parts of a building.
Even if your home looks fine from the outside, there could be hidden damage.
That is why checking your property after a storm is so important. Only inspect areas that are safe to access, and leave dangerous roof or structural damage to professionals.
Does Your Florida Homeowners Policy Cover Hurricane Storm Damage?
The answer depends on your insurance policy and what caused the damage.
Many Florida homeowners insurance policies cover certain types of hurricane damage, especially damage caused by strong winds.
For example, if hurricane winds damage your roof and rain enters through the opening, your policy may cover the resulting water damage.
However, there is an important difference between wind damage and flood damage.
Most standard homeowners insurance policies do not cover flooding caused by rising water or storm surge. That type of damage usually requires separate flood insurance.
Homeowners may have coverage through a private flood insurance company or the National Flood Insurance Program (NFIP), which helps protect eligible properties from covered flood damage.
Florida homeowners may also have a special hurricane deductible. This is the amount they must pay toward covered hurricane damage before their insurance company pays the remaining covered amount, subject to policy limits.
Understanding what your Florida homeowners policy covers can help you avoid surprises when filing a claim.
5 Steps to Take After the Storm to Protect Your Insurance Claim
If Hurricane Isaias damaged your home or business, taking the right steps can help protect your property and insurance claim.
1. Take Photos and Videos of the Damage
Before cleaning up, document everything you can safely see. Take pictures of damaged roofs, ceilings, walls, floors, and personal belongings.
2. Protect Your Property From Further Damage
If it is safe, take reasonable steps to prevent more damage. For example, you may need a professional to place a tarp over a damaged roof. Keep receipts for any emergency repairs.
3. Contact Your Insurance Company
Report the damage as soon as possible. Ask about the claims process and write down your claim number so you can easily track your case.
4. Keep Your Paperwork Organized
Save repair estimates, receipts, photos, emails, and letters from your insurance company. These records may be helpful if questions come up about your claim.
5. Review Your Insurance Company's Decision
If your claim is denied or the payment seems too low, ask for a written explanation. You may want to seek legal advice before accepting a final settlement.
What If Your Hurricane Insurance Claim Is Denied or Underpaid?
Imagine finding out your roof needs major repairs, only to learn that your insurance company is offering much less than the estimated repair cost.
Unfortunately, disagreements over hurricane damage claims can happen.
Insurance companies may:
-
Deny a claim because they believe the damage is not covered.
-
Offer less money than the homeowner believes is needed for repairs.
-
Disagree about whether the damage was caused by the hurricane.
-
Take longer than expected to investigate or process a claim.
A denied or underpaid claim does not always mean the insurance company's decision is correct.
If you believe your insurer overlooked damage or made a mistake, you may have options to challenge its decision.
Do not wait too long to act. Under Florida law, most property insurance claims must be reported within 1 year of the date of loss. Supplemental claims for additional damage generally must be reported within 18 months. Different rules may apply to some policies, including certain flood insurance policies.
Hurricane Isaias Recovery: Get Help With Your Insurance Claim
For Florida families, the days after a hurricane can be stressful. Between cleanup, repairs, and insurance paperwork, there is a lot to manage.
At Vargas Gonzalez Delombard, LLP, we help Florida homeowners and business owners with property insurance disputes, including hurricane damage claims.
If your insurance company has denied your claim, delayed a decision, or offered less than you believe your covered damage is worth, our attorneys can review your situation and explain your legal options.
Was your property damaged by Hurricane Isaias?
Don't let an insurance dispute add more stress to your recovery.
Contact Vargas Gonzalez Delombard, LLP for a free case evaluation.
Every insurance claim is different. Coverage depends on the terms of your policy and the facts of your loss.