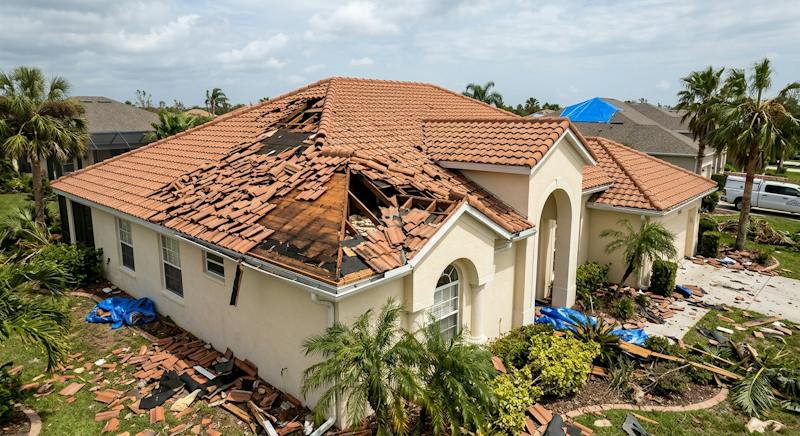
When your home is damaged, you expect your insurance company to help. But the claim process does not always go as planned. Olympus Insurance may deny the claim, take longer than expected, or offer less money than you need for repairs.
If this happens, do not give up. You may still have options. The property insurance attorneys at Vargas Gonzalez Delombard, LLP can review your claim, explain your policy, and help you decide what to do next.
What Coverage Does the Olympus Insurance Company Offer Florida Homeowners?
Olympus Insurance sells homeowners insurance to Florida residents. The exact coverage depends on your Olympus policy. A policy may cover damage caused by events such as:
- Hurricanes and strong winds
- Hail
- Fire and smoke
- Sudden water damage from a covered pipe leak
- Theft or vandalism
- Other reasons
Coverage may include repairs to the Florida home and payment for damaged personal property. Some policyholders may also have endorsements that provide enhanced coverage. However, all Florida property insurance policies have terms, limits, deductibles, and exclusions.
For example, flood damage is usually not covered by a standard homeowners policy. Separate flood insurance may be available through a private insurer or the National Flood Insurance Program. Slow leaks, wear and tear, and poor maintenance may also be excluded.
Read your policy carefully. The cause of the damage is often just as important as the damage itself.
Why Would the Insurance Company Deny a Property Damage Claim?
An insurance company may deny a property claim for many reasons. Olympus may say:
-
The damage is not covered by the policy.
-
The damage happened before the policy began.
-
The homeowner waited too long to report the loss.
-
The damage came from wear and tear or poor maintenance.
-
The repair cost is below the deductible.
-
There is not enough proof of the damage.
-
The homeowner did not follow a policy rule.
A denial does not always mean the insurance company is correct. The company may have missed important facts, misunderstood how the damage happened, or used a repair estimate that does not include all covered work.
Ask for the denial in writing. The letter should explain the facts and policy language used to make the decision. If you believe the claim was handled unfairly, you may also be able to submit a complaint to the Florida Department of Financial Services.
What Is an Underpaid Olympus Insurance Claim?
An underpaid claim happens when the insurance company agrees that damage is covered but does not offer enough money to complete the needed repairs.
For example, Olympus may pay to patch part of a roof while your contractor says a larger repair is needed. An estimate may leave out damaged floors, cabinets, drywall, paint, labor, or the cost of bringing repairs up to code.
The payment may also be reduced by your deductible or depreciation. This can be frustrating when you have paid insurance premiums but still cannot afford the covered repairs. Ask the adjuster to explain every deduction. Compare the insurance estimate with a detailed estimate from a qualified contractor.
Do not assume that the first payment is always the final payment. Some claims may qualify for more money when new covered damage or repair costs are properly documented.
How Long Does Olympus Have to Decide a Florida Property Claim?
Under Florida law, a residential property insurer generally has 60 days after receiving notice of a claim to pay or deny the claim or part of it. Certain events can pause or extend that deadline.
The insurer must also give a reasonable written explanation for a payment, denial, or partial denial. If the claim payment is lower than the insurer's own detailed estimate, the insurer must explain the difference in writing.
Every claim is different. A delay does not automatically mean that the insurance company broke the law. Still, you should keep track of dates and ask for written updates.
What Should Homeowners Do After Property Damage?
Take these steps as soon as it is safe:
-
Protect people first. Leave the home if it is unsafe and call emergency services when needed.
-
Stop more damage. Make reasonable emergency repairs, such as placing a tarp over an opening. Do not make permanent repairs before the insurer can inspect the property unless they are needed for safety.
-
Take photos and videos. Record the damaged areas before cleaning or moving items.
-
Save damaged property. Keep damaged items when it is safe to do so until the insurance company has had a chance to inspect them.
-
Keep every receipt. Save bills for emergency repairs, hotel stays, cleanup, and other costs related to the loss.
-
Report the claim quickly. Olympus says policyholders can report a claim through its insured portal.
-
Write down each conversation. Keep the date, time, name, and main points from every call or inspection.
Florida generally requires notice of a new or reopened property claim within one year after the date of loss. A supplemental claim generally must be reported within 18 months. These rules have details and exceptions, so it is best to act quickly.
What Can an Olympus Customer Do If a Claim Was Denied or Underpaid?
Start by gathering these documents:
-
Your insurance policy and declarations page
-
The denial or payment letter
-
Olympus's repair estimate
-
Photos and videos of the damage
-
Contractor estimates and invoices
-
Inspection or engineering reports
-
Emails, letters, and notes from phone calls
-
Receipts for repairs and other expenses
Then compare the reason given by Olympus with the facts and the policy. As the customer, you can send the company missing records or ask it to review new information. Depending on the claim and the policy, other options may include mediation, appraisal, a supplemental claim, or legal action.
Be careful before signing a release, accepting a final settlement, or starting major repairs. These steps may affect your rights or make it harder to prove the full amount of damage.
When Should You Contact a Property Insurance Attorney?
Consider speaking with an attorney if:
-
Olympus denied your claim.
-
The payment is too low to make the repairs.
-
Important damage was left out of the estimate.
-
The insurer says the damage is old or caused by wear and tear.
-
You keep sending documents but do not receive a clear answer.
-
You do not understand the policy or denial letter.
-
A deadline may be close.
An attorney can review the policy, evidence, and claim history. The attorney can also explain your options, possible compensation under the policy, and how to communicate with the insurance company. Before hiring a lawyer, ask whether a free case review or free consultation is available and how legal fees will be handled.
Talk to Vargas Gonzalez Delombard, LLP About Your Olympus Insurance Claim
You paid for insurance to protect your property. If your Olympus Insurance claim was denied, delayed, or underpaid, you do not have to handle the dispute alone.
The property insurance attorneys at Vargas Gonzalez Delombard, LLP help policyholders understand their rights and pursue the insurance benefits available under their policies. Contact us today for a free consultation about your property damage claim. We can review what happened, explain your options, and discuss any fees before you decide how to move forward.
This article is for general information only and is not legal advice. Reading it does not create an attorney-client relationship. Insurance coverage and legal options depend on the policy, facts, and applicable law.